Seller Solutions
Selling Your Home in Pre-Foreclosure
Behind on mortgage payments? Selling before a foreclosure is completed can protect your credit and any equity you have. We'll explain your options clearly and confidentially.
Pre-Foreclosure
Options, explained confidentially
Falling behind on a mortgage is stressful, and the earlier you explore your options, the more of them you'll have. Depending on your equity and timeline, options may include a traditional sale, a short sale negotiated with your lender, or a loan modification or repayment plan.
If you have equity, a well-priced sale can pay off the loan and leave you with the difference. If you owe more than the home is worth, a short sale, where the lender agrees to accept less than the balance, may be possible.
We'll walk you through the choices without pressure. We also recommend speaking with a real estate attorney and a HUD-approved housing counselor, who can advise on legal and financial questions.
- TimelineForeclosure timelines vary by state; New York and New Jersey are judicial-foreclosure states.
- EquityA traditional sale may let you keep remaining equity.
- Short salesRequire lender approval and can take longer.
- Free counselingHUD-approved housing counselors offer free or low-cost guidance.
We are real estate professionals, not attorneys or tax advisors. Please consult an attorney or tax professional for legal and tax advice.
Free guide
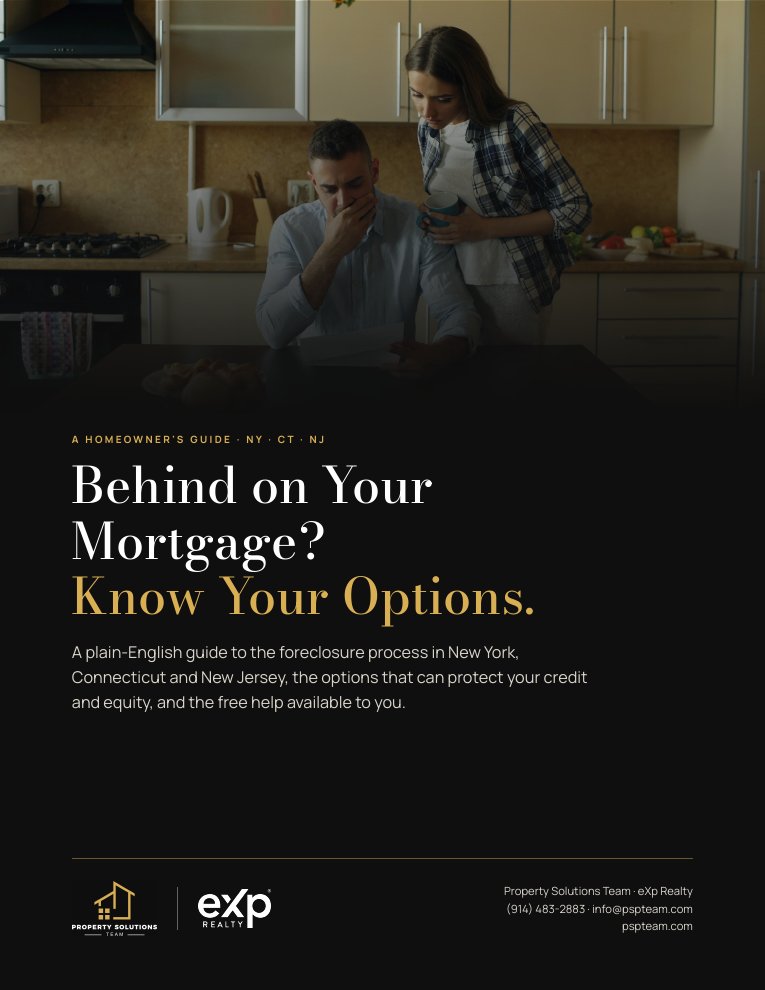
Behind on Your Mortgage? Know Your Options.
Our free, confidential 7-page guide explains how the foreclosure process works in New York, Connecticut and New Jersey, compares your options side by side, includes an equity worksheet and shows you how to spot foreclosure rescue scams.
How we help
Our step-by-step process
- 01
Confidential call
We learn about your situation, timeline and goals, no judgment, no pressure.
- 02
Know your numbers
A valuation and an estimate of what you'd net after the loan and closing costs.
- 03
Review options
Traditional sale, short sale or staying in the home, with input from your attorney or counselor.
- 04
Prepare & list
A pricing and marketing plan built around your timeline.
- 05
Negotiate
With buyers and, for a short sale, with your lender.
- 06
Close
We coordinate with the lender, attorney and title company to close.
FAQ
Pre-Foreclosure: common questions
Can I still sell my house if I'm behind on payments?
In many cases, yes, until the foreclosure is completed. Selling earlier gives you more time and options. Talk with an attorney about your specific timeline.
What is a short sale?
A short sale is when the lender agrees to accept less than the full loan balance so the home can be sold. It requires lender approval and documentation of hardship.
Will selling hurt my credit?
Selling before a foreclosure is completed is generally less damaging than a completed foreclosure, but every situation differs. A housing counselor can advise.
Do you charge anything upfront?
No. We are paid only if the home sells, as agreed in the listing agreement.
Is this confidential?
Yes. We handle pre-foreclosure sales discreetly.
Prefer to talk it through?
Call our team for a confidential, no-pressure conversation about your options.